
Policy Brief
Housing
Contents
Introduction
House prices and rents in Jersey are significantly higher than in the south east of England and Guernsey. Accordingly, the cost of housing is a significant political issue. This paper brings together the available data and analysis on the structure and operation of the housing market and details of government policies on housing.
Summary
- At the 2021 census there were 48,610 housing units. 54% were owner-occupied, 14% were social rented and 32% were private rented. 25% of properties were detached, 20% were semi-detached, 10% were terraced and 44% were flats.
- Landlords owning five or fewer properties account for 70% of the private rented stock. Eight landlords with 50 or more properties account for 5% of the stock.
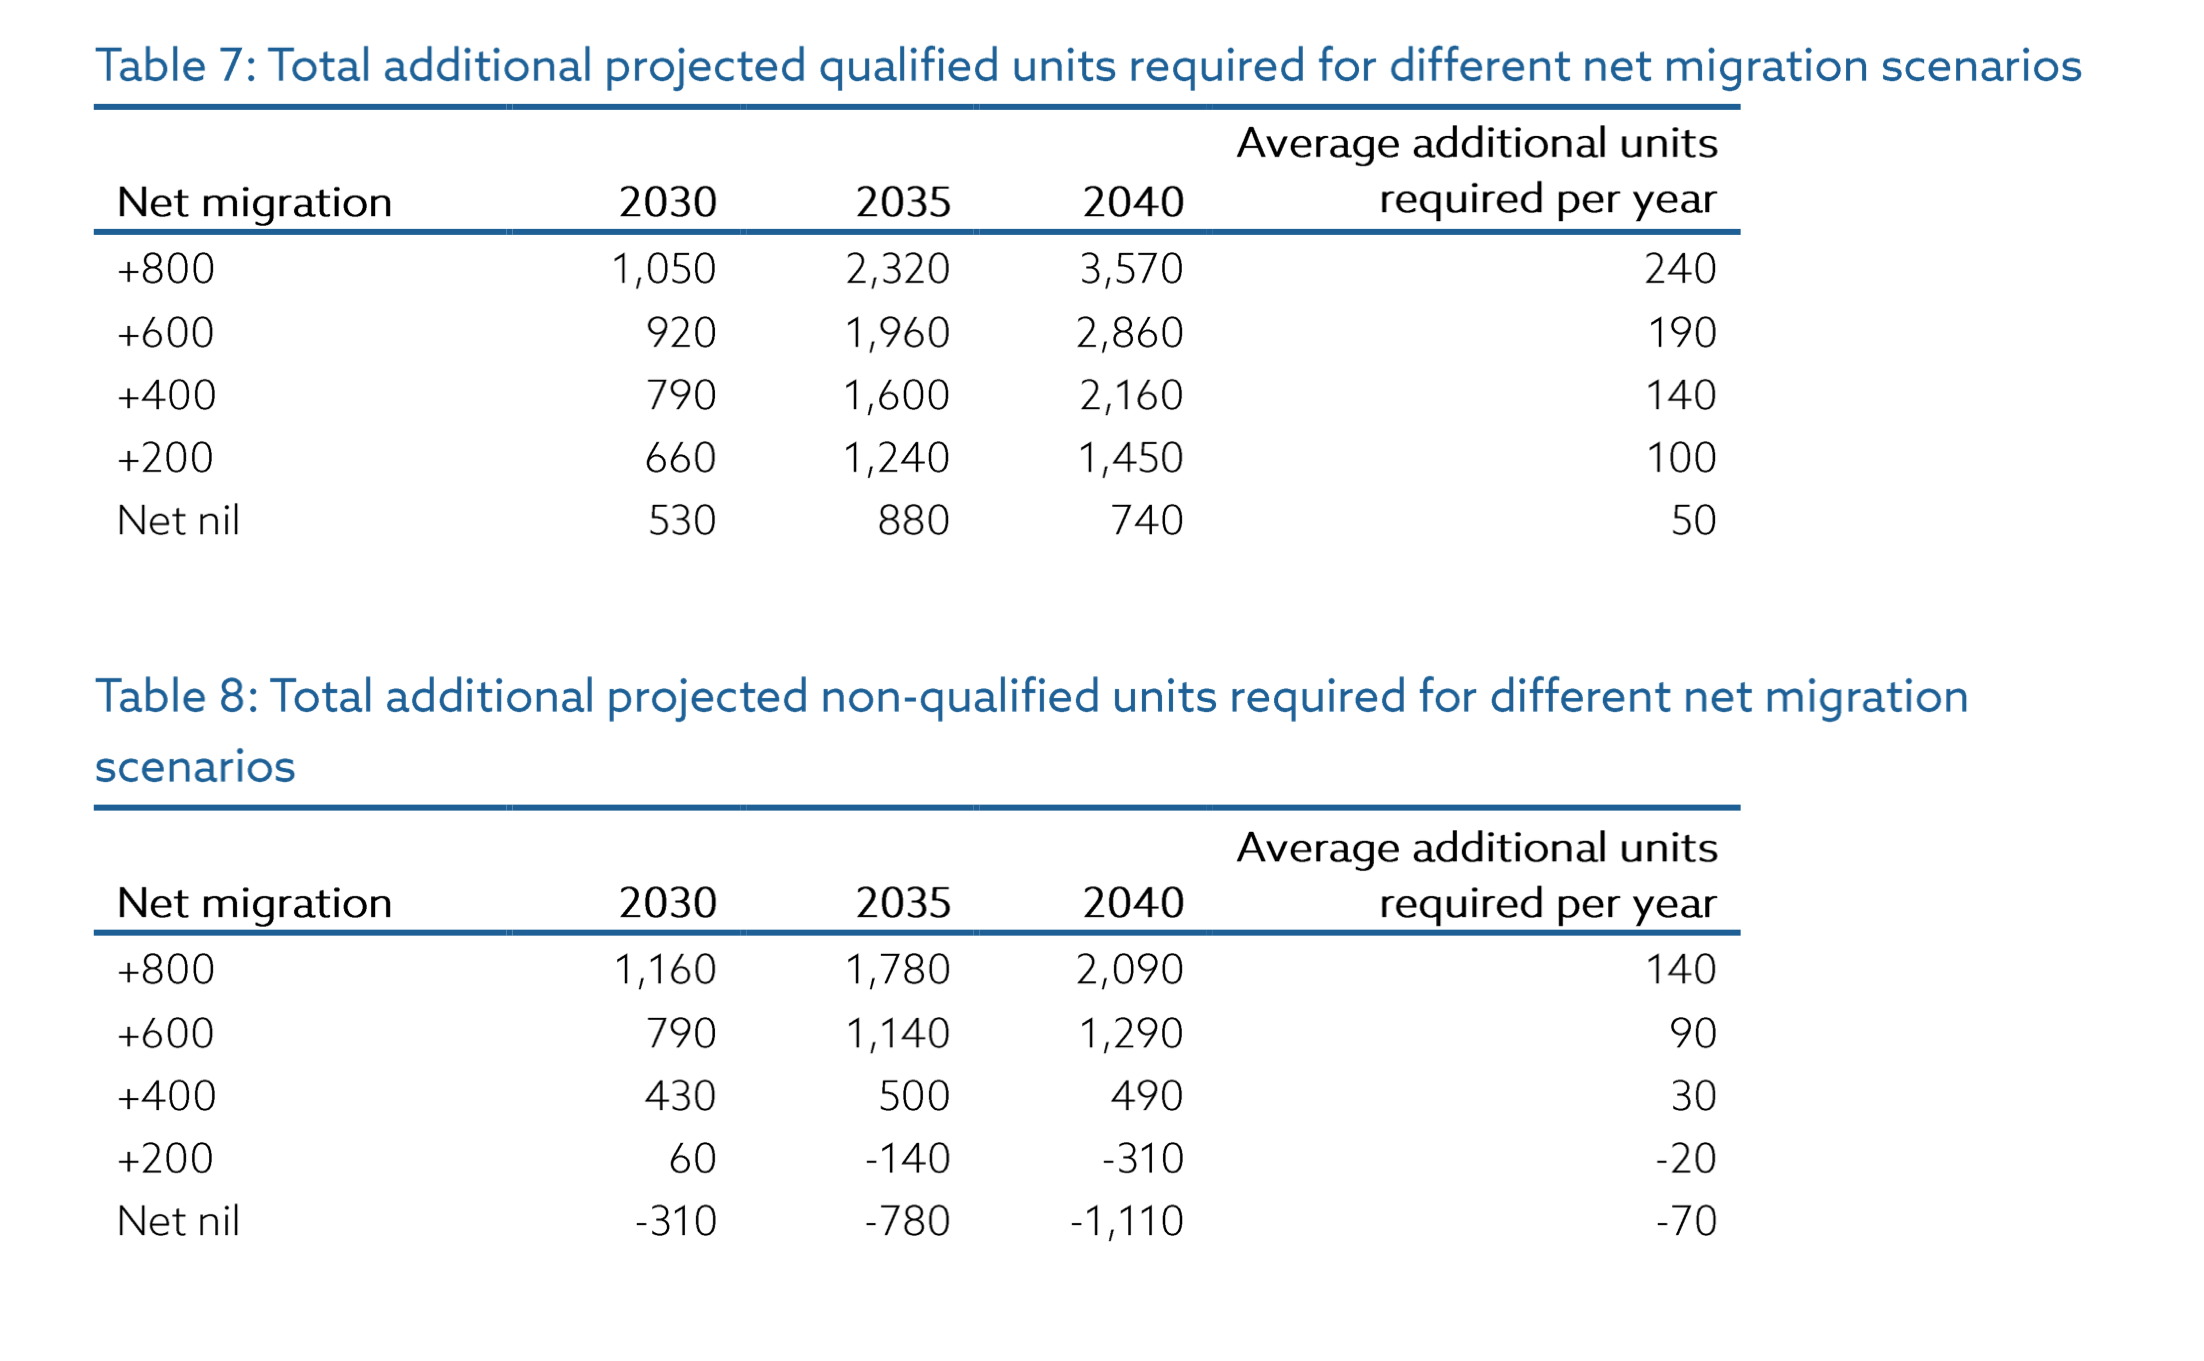
- Housing needs projections suggest an additional 2,000 housing units would be needed by 2035 with a net 325 migration scenario.
- Jersey’s Fiscal Policy panel published a detailed report on the housing market in April 2024. The key conclusion was: “As with all rich economies, spending on housing is a high proportion of income in Jersey. This, coupled with Jersey’s relatively high income inequality (and lack of land borders) means that market rents and house prices are unaffordable for a considerable proportion of the population.”
- Average house prices in 2026 Q2 were 2.2% higher than a year earlier and 12.4% lower than the peak in 2022 Q3. In real terms the reduction was 26.5%.
- Average rents in 2026 Q2 were 2.3% lower than a year earlier and 8.3% lower than the peak in 2022 Q3. In real terms the reduction was 23.0%.
- One of the priorities of the previous Council of Ministers was to “Provide more affordable homes for Islanders and more confidence for the rental sector”. There were two related priorities: “Deliver a plan to revitalise Town” and “Reform the planning service to get Jersey building”.
- One of the priorities of the current Council of Ministers is to “Provide more affordable homes for Islanders and more confidence for the rental sector”. There are two related priorities: “Deliver a plan to revitalise Town” and “Reform the planning service to get Jersey building”.
- Assisted purchase home ownership schemes help first-time buyers who cannot purchase on the open market without assistance. The household income limits for the schemes range from £65,000 a year (one-bedroom flat) up to £135,000 per year (four-bedroom house).
- New laws make it illegal to let a property without a licence.
- Rents charged by social housing landlords are a maximum of 80% of market rent. Eligibility for social housing is restricted to those and with income below a threshold. The current income limits for a single applicant range from £40,000 for those with no children to £87,700 for those with three children.
- A review of social housing rents policy concluded that large-scale structural reforms would create significant administrative complexity and financial uncertainty, with limited additional benefit when the current role of Income Support in supporting eligible low-income households is taken into account. “Targeted amendments to the current rents policy represent the most effective and proportionate way forward.”
The housing stock
Chapter 4 of the Report on the Jersey 2021 Census provides a snapshot of housing in Jersey in April 2021. Key points were –
- There were 48,610 private dwellings and 162 communal establishments.
- The number of private dwellings in Jersey increased by 9% (3,912 dwellings) in the 10 years since the 2011 Census (which recorded 44,698 dwellings).
- 4,027 private dwellings were identified as vacant on Census Day, corresponding to a vacant rate of 8.3%. A quarter (26%) were vacant due to construction work (being built or renovated), a greater proportion than in 2011 (9%). Second / holiday homes (6%) and properties being between tenants (4%) were the next most cited reasons.
- Excluding those living in communal establishments, 101,188 people were living in 44,583 dwellings in 2021, representing an average of 2.27 persons per dwelling. The figure was 2.79 in 1971 and 2.38 in 2001.
- The breakdown of houses by tenure was –
- Owner occupied 54%
- Private rented – registered 22%
- Private rented – unregistered 10%
- Social rented – Andium 10%
- Social rented – other 4%
- The breakdown of the housing stock by type of dwelling was –
- Detached 25%
- Semi-detached 20%
- Terraced 10%
- Purpose built flat 31%
- Flat as part of converted house 11%
- Flat in commercial building 2%
Statistics Jersey has published in the House Price Index Fourth Quarter 2025 report data on the breakdown of landlords by the number of properties that they own. The data are drawn from the rental properties licensing scheme.
It is estimated that the rental housing stock comprised 18,415 units at the end of December 2025. 6,987 (38%) were social housing or publicly owned units. The remaining 11,428 (62%) were owned by private landlords.
The following table shows the breakdown of the private rental stock by number of properties owned.
Properties owned by private landlords, December 2025
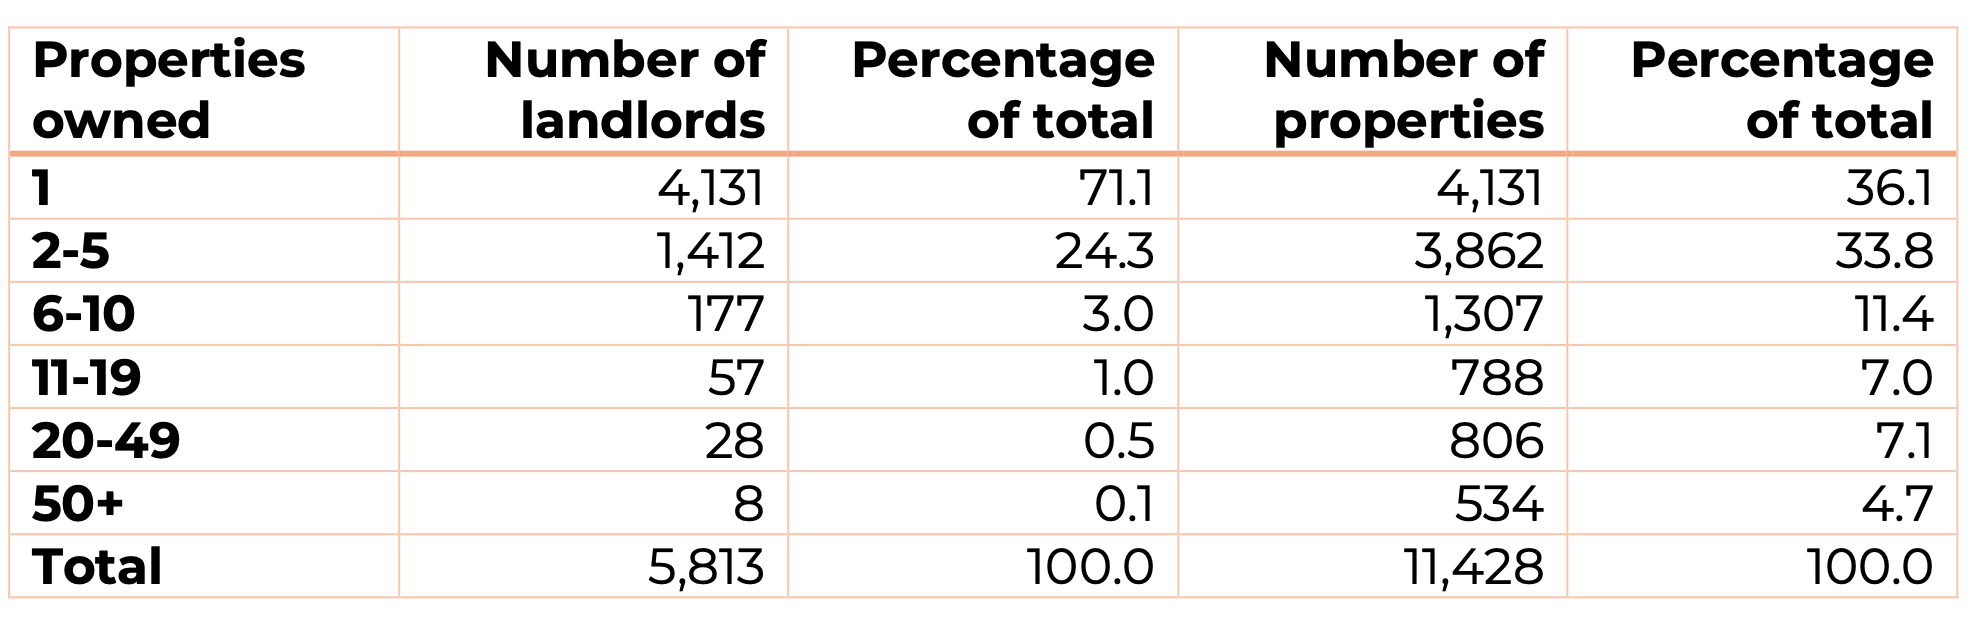
It will be seen that 36% of private rental properties were owned by landlords with just one unit and 70% by landlords with five or fewer properties. Eight landlords owned 50 or more properties, accounting for 4.7% of the stock.
Future housing needs
On 25 February 2026 Statistics Jersey published Jersey households and housing needs projections 2025 to 2040. The introduction to the report states –
This report has been produced based on the latest Population projections 2025 to 2080 by Statistics Jersey. Projections for the total number and type of households are provided up to 2040. The changes in household structures seen across the 2011 and 2021 census are used to inform these projections. The projection range is shorter than the population projections, which run to 2080, due to household projections being particularly sensitive to policy changes and household composition assumptions making longer term projections potentially unreliable.
It is important to note that the projections are not forecasts and so will differ from the actual future outcomes. They assume that current trends and behaviour in respect of fertility, mortality, migration and household formation continue forward over the projection period. Changes to these assumptions will impact the results, therefore the findings should be considered an estimate based on recent trends to inform decision making. For more on this please see the separate methodology document .
The report also uses the change in the numbers and types of households to provide an objective assessment of future housing needs over the projection period and includes breakdowns of the projected change in the numbers, type, and size of dwellings. This assessment is based around the existing distribution of property type to households as observed in the 2021 Census. It is based solely on the projected demographic change and assumes that the distribution of households to property type size remains the same as was observed in the census.
The projections are presented as a series of scenarios based on a set level of net migration experienced every year over the projection period. These are:
Net nil migration, where the number of people arriving equals the number of people leaving
+ 200 net migration, where 200 arrive on the Island over and above the number that leave
+ 400 net migration
+ 600 net migration
+ 800 net migration
The headlines in the report are –
The household and housing needs projections indicate that for a +400 net migration scenario:
-
- the number of households will increase from just under 47,000 in 2025 to over 49,000 in 2040
- 140 qualified and 30 non-qualified additional units of accommodation would be required each year
- across the period to 2040, a total of 680 additional qualified 3-bed houses, and 500 additional qualified 1-bed flats would be required.
Two tables from the report are reproduced below.
Fiscal Policy Panel Housing Market Review
On 16 April 2024 Jersey’s Fiscal Policy Panel published Housing Market Review . This was in response to a request by the Chief Economic Advisor for support in understanding the economic drivers underlying the challenges being experienced in Jersey’s housing market. The report provides a comprehensive description of the structure of the Jersey housing market as well as analysis of housing market problems.
The executive summary of the report is set out in full below –
As with all rich economies, spending on housing is a high proportion of income in Jersey. This, coupled with Jersey’s relatively high income inequality (and lack of land borders) means that market rents and house prices are unaffordable for a considerable proportion of the population.
- Jersey’s housing supply has expanded. The rate of new housing supply in Jersey was higher than the OECD average in 2011, though fell below the average in 2021.
- The housing stock has changed. Growth in housing stock has been concentrated in purpose-built flats, accounting for 75% of the increase in properties from 2011 to 2021.
- Jersey has a lower homeownership rate than the UK. 54% of households own their own properties. This compares to 67% in the UK. This is partly affected by restrictions on who can buy property in Jersey.
- Around 8% of properties are vacant in Jersey. This is surprisingly high given the Island’s small land mass and supply constraints.
- Overcrowding, while a problem for those experiencing it, is not particularly common in Jersey. The same proportion of households are classed as overcrowded (having fewer bedrooms than required by the household) as in England and Wales. However, under-occupation, where a household has at least two bedrooms more than required, is less likely in Jersey.
- Access to mortgage finance has Jersey specific features not seen in the UK. There are fewer mortgage providers, and the process for accessing a mortgage is more personal, and lender specific, potentially raising switching costs. Borrowers are likely to face higher mortgage interest rates compared to the UK mortgage market.
- Environmental restrictions in Jersey present hard limits to development.
- Development is restricted outside of the built-up area, which covers 12% of the Island. These restrictions are justified by conservation but represent a constraint on the amount of new housing supply that can be generated.
- The planning system can also create barriers to new housing supply.
- Features of the system, such as third-party appeals and delays in reaching decisions on major applications, create uncertainty over outcomes and act as barriers to bringing new supply forward.
- Housing supply targets are difficult to develop. They are based on estimated future housing demand which is inherently uncertain. They may need to be reviewed when population growth or demographic trends differ from forecasts, as they have done in recent years.
- Affordability is at historically low levels. House and rental prices rose faster than incomes over the 8 years to 2022. An average priced house is equal to more than 13 years of net income for the average household, and this is compounded by recent rises in mortgage rates.
- The rise in prices has many causes. They include a period of global record-low interest rates, rising income growth and demographic change. While these factors supported demand, others have tamped down on supply, including the fall in the rate of home completions from 2012 to 2021 compared to the previous ten years.
- A high-cost housing market can harm any economy. Sustained productivity growth relies on a fluid job market in which the most productive firms can grow by hiring. Even the most successful businesses in Jersey are finding it increasingly difficult to attract and retain staff. This holds back their expansion, with knock on effects for productivity, output and ultimately living standards on the island.
- The Panel’s assumption is for house prices to remain stable in 2024. However, there is a risk that prices may fall in the short-term. Affordability is unlikely to change in 2024 with base interest tariffs not forecast to fall until the middle of the year and inflation outpacing earnings growth. As these factors begin to ease, prices could again increase, particularly without higher rates of supply.
The Report then lists a series of key findings, which are reproduced below –
Jersey’s housing market is not exceptional – many other places face similar problems. But particular groups are struggling. There are several areas that would benefit from further work. These should be prioritised in terms of those that are genuinely holding back new arrivals and young Islanders from accessing housing, since the problems faced by these groups are those most likely to be holding back economic activity on the island.
1. Social housing. High economic inequality and high housing costs increase the need for a portion of the population to access housing at below market rent. Thus, although Jersey’s share of social housing is above the OECD average, focus on delivery of housing below market rent, including key worker accommodation and social housing, would be welcome.
2. Planning. The FPP notes that some features of the planning process in Jersey can increase uncertainty of outcomes, such as third-party appeals. The Panel recognises that there are barriers to data collection for the planning department. Greater data, such as on the length of time from registration of application to final decision, would help to ensure the planning process is efficient and low cost for the applicant.
3. Mortgage markets. The Panel notes that some features of the mortgage market in Jersey, such as the low number of lenders, barriers to switching and higher interest rates compared to the UK, are concerning. Further work investigating the impact of the market on interest rates and product choices offered to Islanders would be beneficial. Systematic data should also be collected on housing arrears and repossessions.
4. Tax measures. The Panel welcomes the phasing out of mortgage interest relief for owner occupiers. This area would benefit from further work to ensure wider taxation measures do not skew the balance between owner occupation and rental.
5. Rental markets. Rental data relies on advertised private rental statistics, which do not reflect actual rents. Data collection on the operation of the rental market would inform understanding of rental affordability and how rental yields compare to other investments over time.
6. Residential status. The seasonal labour force is important to Jersey’s economy. There needs to be greater understanding of the changes in the population by residential status and the interaction of this with housing supply, to understand if planned future housing supply is reflective of expected changes in residential status.
7. Residential space standards. Minimum space standards should consider harmonisation with the UK where possible to encourage use of more standardised construction methods such as modular units. These types of construction methods support the efficiency of building by requiring less labour on island. Though, standards are not the only barrier to such methods.
8. Demand measures. Interventions that slow down adjustment of the housing market to changing economic conditions are not desirable.
9. Vacant homes. There is room for improvement in Jersey’s rate of home vacancy. The Panel notes that the Government, through the launch of the Empty Homes Service, is working to identify long-term vacant properties and bring them back into use. Bringing vacant properties back into use is welcome in a supply-constrained area.
10. Distribution of housing. Given the significant increase in the share of flats in the Jersey housing stock over recent years, it is important to monitor the relative supply and price of each type of housing to ensure all needs are met.
Housing costs
Statistics Jersey publishes quarterly reports on housing costs. The most recent report, published on 6 August 2026, wasfor the second quarter of 2026. Key points from this report were –
- Average house prices in 2026 Q2 were 7.1% higher than in 2026 Q1 and 2.2% higher than a year earlier.
- Average rents in 2026 Q2 were 3.6% lower than in 2026 Q1 and 2.3% lower a year earlier.
- The turnover of properties was 32% higher in 2026 Q2 than in 2026 Q1 and 24% higher than a year earlier. Turnover remains below historic levels.
Changes in house prices and rents vary considerably in the short term. Typically, rents are “stickier” than house prices. When house prices rise rapidly rents rise more slowly; conversely when house prices fall rents fall more slowly. In the long term the two variables are closely correlated as they are different ways of paying for the same commodity. Between 2002 and 2026 Q2 average house prices rose by 122.8% and rents by 111.9%.
The following table shows mean prices for 2026 Q2 for different types of unit and the change from 2025 Q2 –
1-bedroom flats £326,000 +5.2%
2-bedroom flats £580,000 +12.8%
2-bedroom houses £601,000 +10.5%
3-bedroom houses £797,000 +8.6%
4-bedroom houses £1,122,000 -2.6%
The relatively small sample sizes mean that all these statistics should be viewed with caution. The average figure for four-bedroom houses is particularly volatile. In 2025 Q1 the average price was £1,405,000 while in 2024 Q4 it was £1,031,000, almost the same as in 2026 Q2.
The fall in house prices and rents has occurred at a time of high inflation generally. In nominal terms average house prices have fallen by 12.4% since their peak in 2022 Q3. Inflation in that period has been 19.1% so in real terms house prices have fallen by 26.5%. Average rents have fallen by 8.3% since their peak in 2022 Q3 and in real terms by 23.0%.
The following table compares average house prices in Jersey with those in the UK.
Mix-adjusted average house prices, Jersey and UK, Q4 2025
| Region | Average house price | Jersey as % |
| Jersey | £565,000 | 100 |
| UK | £271,000 | 208 |
| England | £293,000 | 193 |
| London | £556,000 | 102 |
| South East | £382,000 | 148 |
Source: Statistics Jersey. Housing Affordability webpage.
It will be seen that house prices on average are comparable with those in London and are 48% higher than those in the rest of the south east of England.
Statistics Jersey calculates that, on a comparable basis, in 2025 Q4 house prices in Jersey were 16% higher than in Guernsey.
Detailed statistics on housing affordability are included on the Statistics Jersey Housing Affordability webpage. This shows that in 2025 average house prices were 5.39 times higher than in 1990 compared with increases of 4.28 times for average earnings and 3.64 times for retail prices.
The webpage includes a housing affordability index. The net index showed –
2003 90.6
2008 64.6
2012 92.3
2023 55.1
2024 62.2
2025 70.3
Affordability was highest in 2003 and 2012 and reached low points in 2008 and 2023. It improved significantly in 2024 and 2025 as a result of house prices falling by 9.1% and earnings rising by 11.1%.
Developments in the housing market reflect factors external to Jersey and are replicated in the UK and other countries. The Russian invasion of Ukraine and other factors resulted in a sharp increase in inflation. The annual rate increased from 0.9% in the year to December 2020, to 12.7% in the year to December 2022, before falling to 2.8% in the year to December 2025. The current forecast by the Fiscal Policy Panel is that the rate will average 3.0% in 2026. However, the effect of the Middle East War is likely to increase inflation above previously expected levels.
An essential tool to bring down inflation is interest rates. Accordingly, in a period of just 18 months the Bank of England base rate increased from 0.1% to 5.25% in August 2023, before falling to 3.75% in December 2025. This has naturally fed through to mortgage rates. Two-year fixed rate mortgages increased from around 2% at the beginning of 2022 to a peak of 6% since when they fell to between 4.34% (under 75% loan to value ratio) and 5.08% (90% loan to value ratio) at the end of 2025. However, the Middle East War has pushed rates up again to an average of 4.8% and between 5.3% and 5.7% respectively. Mortgage rates are at least 0.5 percentage point higher in Jersey than in the UK.
Higher interest rates combined with a previously overheated housing market in Jersey have led to the reduction in house prices and rents.
The rise in interest rates is impacting most severely on those who bought housing between 2020 and the early part of 2023. For a typical borrower rolling off a fixed-rate deal in 2026, interest payments are increasing by an average of about £3,600 a year – but for a relatively small number of households the figure will be more than £10,000 a year.
Priorities
The Common Strategic Policy of the current Council of Ministers, published in May 2024, set out 13 priorities for delivery in the next two years. They include –
Provide more affordable homes for Islanders and more confidence for the rented sector.
Related to this are two other priorities –
Deliver a plan to revitalise Town.
Reform the planning service to get Jersey building.
The section on housing is –
Provide more affordable homes for Islanders and more confidence for the rental sector
Nearly half of households in Jersey live in rental accommodation and it is vital we ensure everyone has access to a safe, secure, and affordable home that meets their needs. The rental market plays an important role in helping us to achieve this, but it must be supported by a modern and fit-for purpose legal framework that helps to protect both tenants and landlords.
We will provide more confidence for the rental sector by implementing the new Rented Dwellings Licensing Scheme to ensure that rental homes are maintained to a decent and safe standard. We will introduce a new Residential Tenancy Law that will improve tenancy arrangements for both tenants and landlords. Ministers will be focusing the Government’s development and planning resources on encouraging the building of more affordable homes for Islanders to buy or rent.
Meeting this priority will provide the certainty and protection both renters and landlords need, tackle rent inflation, and – as more social housing supply is provided – make the benefits of social housing accessible to more Islanders. All of this will be driven forward by the Housing Crisis Emergency Taskforce which was established on the first day of this Government’s term.
Assisted home ownership schemes
Assisted purchase home ownership schemes help first-time buyers who cannot purchase on the open market without assistance. The household income limits range from £65,000 a year (one-bedroom flat) up to £135,000 per year (four-bedroom house).
Under the Andium Homebuy scheme buyers can purchase a home with a deferred payment of up to 25% of the market value. The number of properties available under the scheme is limited. The website shows that estimated wait times for the scheme range from 1 year for a one-bedroom flat to three years for houses with two or more bedrooms.
On 29 February 2024 the first step assisted home ownership scheme was opened. The Government press release stated –
The assisted purchase home ownership scheme, delivered in partnership with Andium Homes, uses £10m of government funding to help eligible Islanders access a contribution of up to 40% towards the purchase of an open-market property.
Buyers will need to provide a 5% deposit towards the purchase and be able to access the maximum lending available to them from one of the scheme’s partnering mortgage lenders.
Residential tenancy law
On 12 September 2025 the States Assembly approved the Residential Tenancy Law (Jersey) Amendment Law 2025. This amends the Residential Tenancy Law (Jersey) 2011. The new law comes into effect on 15 April 2026. The Government announcement of the commencement date said that the law “strengthens protections for both tenants and landlords, and creates clearer processes around notice, tenancy types, and rent increases. The reforms also establish the new Rent Tribunal, which will provide an independent route for tenants to challenge rent increases within a tenancy.”
On 12 March 2026 the Government published guidance on Tenant and landlord rights.
The Government also published Guidance for the residential tenancy law. Following is a summary of the key changes to previous arrangements –
- Periodic tenancies (those with no fixed end date) are intended to be the default form of tenancy agreement; however, landlords and tenants may still agree an initial fixed term of up to 3 years at the start of the tenancy. When that fixed term ends, the tenancy will either end (if notice is given) or automatically convert into a periodic tenancy if it continues.
- Fixed-term tenancy agreements must clearly set out what each party must do if the tenancy is to end early.
- Landlords will need to give a reason for ending the tenancy, unless they are issuing a year’s notice.
- A landlord can regain possession in three main ways:
- On mandatory grounds, with reason-based notice, and the Court must grant possession if notice is given lawfully. However, the court still retains discretion in ordering a stay of eviction.
- On discretionary grounds, with reason-based notice, if notice is given lawfully and the Court decides possession is reasonable.
- Using other lawful routes, with no reason required, but all notice and procedural requirements have been followed.
- Within tenancies, rent can only be increased once per year, with 2 months’ notice, and by no more than Jersey’s Retail Prices Index (RPI) unless the rent has been significantly below the market rent, or the property has been improved to the tenant’s benefit.
- Landlords remain free to set the starting rent for a new tenancy – i.e. with a new tenant – at a rate they see fit.
- An independent Rent Tribunal will be available to help resolve disputes about the lawfulness of rent increases.
Private rented dwellings licensing scheme
Since 1 August 2024 it has been illegal to let a property without a licence. The details of the scheme and other relevant information are set out on a page Rented dwelling licensing on the government website.
To qualify for a licence rental property must meet minimum standards including –
- An electrical safety report undertaken by a competent engineer.
- An annual gas safety inspection, even if a gas appliance is not connected or in use.
- A smoke detection alarm.
- A carbon monoxide detection alarm.
A copy of the licence and written information explaining how tenants can raise a concern or complaint must be provided to tenants within 28 days. The tenancy agreement has to be in writing and tenants must be provided with a condition report.
Access to social rented housing
The issue of whether housing being built should be “affordable” comes up in political debate. There is the ordinary meaning of affordable but also in the context of the Jersey housing market, “affordable” means homes available from social landlords at 20% below market rent. Access to such homes is through the Affordable Housing Gateway . To qualify applicants must be –
- Medically exempt from working with a need for specific types of housing that cannot be afforded in the private sector, or
- have a family and be in receipt of a relatively low income, or
- are over 18 and in receipt of a relatively low income.
The current income limits for a single applicant range from £40,000 for those with no children to £87,700 for those with three children. For joint applicants the range is from £54,000 to £94,800. For comparison, the mean household income in Jersey is currently around £78,000.
It does not follow that being in the Gateway automatically qualifies a person for social housing. This depends on the availability of homes. The Gateway is divided into four bands – urgent need, moderate need, low need and general. The Affordable Housing Gateway Month-end Statistics report as at 31 January 2026 showed that were 614 cases in the Gateway of which 218 were classed as urgent.
Social rented housing rent policy
On 28 January 2026 the Housing Minister published Review of social housing rents – Options for a revised social housing rents policy. The report was accompanied by five thematic background papers that provide an evidence base on various aspects of social housing provision –
Review of social housing rents: understanding social housing in Jersey
Review of social housing rents: evidence on housing affordability
Review of social housing rents: the Income Support system
Review of social housing rents: insights from social housing providers
Review of social housing rents: alternative social housing rental models
Collective, the papers provide comprehensive analysis of the social housing sector, rent policy and the interaction of rent and income support policy. This section provides key extracts from the papers.
The executive summary of Review of social housing rents: understanding social housing in Jersey is set out below –
- Social housing in Jersey has traditionally provided homes to lower-income households, with eligibility determined by factors such as age, income and household composition. Historically, access to social housing has been limited due to constrained housing supply. However, recent increases in Jersey’s social housing stock have enabled the Minister for Housing to widen eligibility criteria.
- These policy changes reflect a gradual shift from a social housing model focused solely on supporting lower-income households towards one that addresses a wider range of housing needs.
- The current social housing rents policy is a key component of the framework underpinning social housing. Initially set at 90% of market value when introduced in April 2014, rents were revised to 80% of market value in January 2021.
- When the policy was introduced in April 2014, existing tenancies were protected from the policy. This has resulted in some tenants living in homes where rents are significantly below market levels – sometimes as low as 50% of market value – and where they may be under-occupying homes where there is demand from new applicants. This outcome reflects a protective measure that was not envisaged to remain in place for more than a decade.
- The existing market-based rental model aims to balance affordability for tenants with the financial sustainability of social housing providers, ensuring sufficient rental income to deliver housing services, maintain existing housing stock and develop new homes.
- Income Support policies are designed to work alongside the rents policy by providing a targeted, means-tested system for households who require financial assistance with their rents. The housing component of Income Support is available for the full amount of rent in social housing, subject to means-testing, whereas for tenants in the private sector the component is capped.
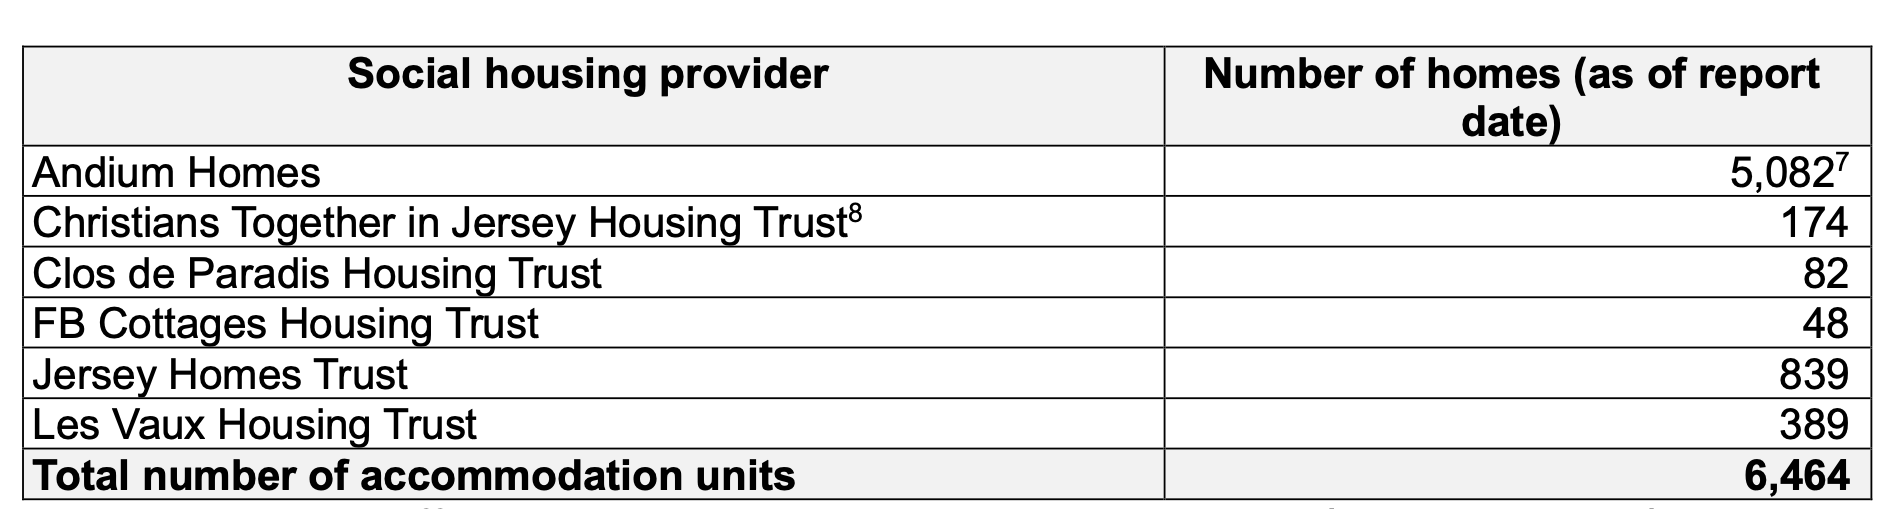
The paper includes a table of Jersey housing providers as at November 2025 –
Notes:
7. The Andium Homes total number of homes does not include 32 owned by the Parish of St. Saviour and managed by Andium Homes.
8. Christians Together in Jersey Housing Trust’s housing stock is to be transferred to Andium Homes.
Andium Homes, a States-owned entity, was established in 2014 to replace the former Housing Department and took over the stock managed by the department. The five independent Housing Trusts were established with the social purpose of providing homes to Islanders in housing need.
The paper sets out the key elements of social housing rents policy –
(a) Rents for new tenancies set at up to 80% of equivalent market value.
(b) Social housing providers may charge below 80% of market value at their discretion.
(c) Existing rents may increase gradually to reach 80% of market value.
(d) Where rents for existing tenancies are above 80% of market value, they must be frozen at their current level until they become equal to or less than 80% of market value.
(e) Rent increases should be limited to no more than once per year in line with the terms of a tenancy.
(f) Social housing providers may freeze or reduce rents if they wish to do so.
Andium is subject to an additional requirement set by the Housing Minister that annual rent increases must be within a range of 2.5% and 4.0%.
The paper includes details of the significant change in social housing provision agreed in 2013, a description of the development of policy on social housing rents and also a detailed chronology of events and policy changes.
The summary of Review of social housing rents: the Income Support system is set out below –
- Income Support provides a sole, unified system to assist Islanders with essential living costs, including housing costs through the housing component.
- Whilst the 30% rental stress calculation can indicate that a household is experiencing financial pressure, this measure is insensitive to the way in which housing is subsidised, and may not provide meaningful results where the housing support is provided through benefit payments.
- In Jersey, Income Support benefits can contribute to covering some, or all, of these housing costs.
- Eligible social housing tenants have their full rent included in their Income Support calculation if their home has the right number of bedrooms for their needs
- Eligible private sector tenants can have their full rent included in their Income Support calculation up to a capped amount.
- Assessing housing affordability requires a clear understanding of how policies, including the payment of Income Support benefits, interact with household incomes, housing costs and non-housing costs.
The paper explains how the income support system works –
Income Support payments are calculated by comparing a household’s income and assets against its assessed needs. If a household does not have a sufficiently high income compared to these needs, the Income Support benefit can provide a payment to top up the household’s income. A household’s Income Support entitlement comprises different allowances called components , each targeting a specific need such as basic living costs, housing, childcare or impairment-related components. This structure makes it easier to assess a household’s eligibility for Income Support, and to provide an appropriate allowance to meet each of these needs.
There is cap on the amount of rent that can be met by income support in the private rental sector but no cap in the social rented sector.
The paper includes an important section on the effect of income support on housing costs and affordability measures –
The housing component is one of the components that makes up an eligible households’ Income Support entitlement. This component directly reflects the cost of the rent as part of an overall benefit calculation. The full rent for social housing tenants is included in their entitlement calculations without limit, and the full rent up to a capped amount is included for private tenants.
Where, for example, a social housing tenant has a proportionally high rent of over 30% of their gross income, an income-to-rent ratio measure assumes ‘rental stress’. However, this high proportion of rent is also reflected in the housing component when Income Support calculate the benefit they receive. Essentially a relatively high rent results in a relatively high benefit provided through the housing component, and a proportionally high rent results in a proportionally high housing component relative to their overall entitlement, and overall income.
The benchmarking of the housing component to the rent effectively offsets the sense of financial strain that can be indicated through ‘ rental stress’ income-to-rent ratio measurements.
In relation to any rent increase, as the housing component of Income Support adjusts in direct alignment to rent changes, this ensures that any increase in rent is matched by an equivalent increase in benefit. Whilst this will reach a cap or limit for those in private rented tenures, it is uncapped for those in social housing, meaning that all the rent is reflected in their benefit calculation regardless of increase.
When rent goes up, benefits increase by the same amount, meaning that the household’s actual residual income stays the same and they have the same money left over after rent has been paid.
If looking at this through a proportional measure, such as income-to-rent ratio measurements, it can appear misleading as the higher rent is now a larger percentage of their income and so assumes higher ‘rental stress’, even though their real situation hasn’t changed and the actual financial impact on the household is neutral.
The summary of Review of social housing rents: evidence on housing affordability is set out below –
- Housing affordability refers to a household’s ability to meet housing costs without causing financial pressure. When costs are too high, a household may face housing stress – or rental stress – which can limit its ability to afford other essential living costs.
- Measuring housing affordability is complex, as it depends on the interplay between household income, housing costs and other essential living costs, all of which vary significantly across different household types and circumstances.
- Three main measures are commonly used to assess housing affordability:
- Expenditure-to-income ratios: These use simple benchmarks – e.g. the 30% rule, or the 30:40 indicator – but they do not fully reflect individual household needs and the effect of financial assistance such as Income Support benefits.
- Residual income: This assesses the income a household has remaining after its housing costs are paid to reflect if there is enough income left over to cover non-housing essentials. This can offer a wider insight into potential financial pressure; however, it may misattribute general cost-of-living challenges to housing costs .
- Subjective measures: These capture the lived experience and perceived financial pressure of households. Whilst valuable, they can be influenced by individual expectations and broader economic conditions.
- No single measure is sufficient. A combined approach using all three provides a more comprehensive understanding of housing affordability, supporting more effective policy design and delivery.
- Income Support helps to offset housing costs for eligible low-income households. As a result, affordability measures should be interpreted carefully as households may appear under financial pressure when their housing costs are largely covered by Income Support.
A key point is that in measures of affordability, in particular a comparison of rents to income, any income support is added to total income. So, for example a person pay a rent of £12,000 a year and earning £24,000 who qualifies for income support will be deemed to have income of £36,000 and their rent will represent one third of their income suggesting that may be in “rental stress” even though all of the rent is met by income support.
The paper’s conclusion is –
Together, these measures [of housing affordability] indicate that lower-income households, particularly those living in private rental accommodation and social housing, are more likely to experience financial pressure. However, the extent of this financial pressure is shaped not only by housing costs but also on household incomes and wider cost-of-living challenges.
The evidence suggests that housing affordability should, therefore, be understood as an interaction between household income, housing costs and other essential living costs. This is also influenced by individual circumstances and policy interventions. Income Support, for example, significantly reduces financial pressure for many social housing tenants, but its impact is not generally reflected in standard housing affordability measures.
Therefore, to be relevant for policymaking in Jersey, housing affordability measures must reflect housing market conditions, broader living costs and the effects of policy interventions, including eligibility for social housing, the social housing rents policy and related Income Support policies.
Review of social housing rents: insights from social housing providers has summaries of specific points which are set out below –
Experience of rental stress
- Social housing providers report no widespread concerns about rental stress, largely because the housing component of Income Support covers all or part of the rent for the majority of tenants.
- However, financial pressure may still arise from broader cost-of-living pressures, suggesting a potential need to review the non-housing components of Income Support.
- Income Support is widely regarded as the most effective mechanism for managing housing costs and ensuring the sustainability of social housing providers.
- Targeted improvements to existing policies, rather than major policy changes, are seen as the most appropriate way to address any financial pressures experienced by tenants.
The delivery of social housing and unintended consequences
- The social housing rents policy, together with Income Support, provides social housing providers with financial stability and certainty, enabling them to provide housing services, maintain and refurbish existing homes, and develop new homes.
- Rising operational and capital costs are outpacing rental income, placing increased financial pressure on social housing providers. Major changes to the social housing rental model risk exacerbating these pressures and undermining long-term financial viability.
- Reducing rental income would likely compel social housing providers to either scale back expenditure or seek alternative funding options, including options such as capital investment from government. This could impact service delivery and their future development plans.
- Unintended consequences of the policy include disincentives for tenants to right-size, and barriers to transitioning from the historic rent structure to the 80% of market rental model.
Potential amendments to the social housing rents policy
- Social housing providers generally favour targeted adjustments to the current social housing rents policy and related Income Support policies, rather than pursuing comprehensive reform.
- Instances of financial pressures amongst tenants may indicate a need to reassess the interaction between the rents policy, Income Support and its non-housing components.
- Reducing rent levels (e.g., to 70% of market value) could benefit tenants who do not receive Income Support. However, for the majority of tenants whose rent is fully or partially covered by Income Support, the impact would be neutral.
- Greater flexibility in the rents policy may be necessary to reflect rising costs facing social housing providers, and to support their financial sustainability.
Issues and opportunities of alternative social housing rental models
- An income-based rental model could offer a more responsive approach to setting rents, aligning them more closely with tenants’ actual ability to pay.
- However, implementing such a model carries significant risks: administrative complexity, data reliability and financial unpredictability. To mitigate these risks, government support would be essential to offset financial uncertainty.
- Income Support already performs a similar function, assessing eligibility for rental assistance. Introducing an income-based model alongside it could duplicate processes, create confusion for tenants, and require substantial investment in staffing and IT systems.
Conclusion
- Social housing providers broadly support the current social housing rents policy, where rents are set at up to 80% of market value. This approach has proven effective in delivering affordable, good-quality homes for tenants, whilst also generating stable and predictable rental income for social housing providers. The financial certainty offered by the rents policy underpins long-term planning and facilitates access to borrowing, enabling social housing providers to maintain existing social housing stock, deliver housing services and invest in the development of new homes.
- However, social housing providers have raised concerns about intensifying cost pressures and a range of unintended consequences that may compromise the long-term sustainability of the rental model. In response, they have identified targeted policy adjustments that could improve the model for both tenants and social housing providers. These include:
- better aligning rent and Income Support payment cycles;
- enhancing support for tenants transitioning from the private rented sector into social housing;
- incentivising right-sizing through the rents policy; and
- introducing flexibility in the rent cap to reflect rising operational and capital costs.
The summary of Review of social housing rents: alternative social housing rental modelsis set out below –
- Five core social housing rental models have been identified across 12 countries: market-based, income-based, cost-based, characteristic-based and formula rent models.
- Most countries use dual or hybrid rental models, combining different rent-setting methods and funding mechanisms to balance affordability, financial sustainability and broader social
outcomes.
- Government funding is a consistent feature of all rental models, delivered either through welfare payments to tenants or direct subsidies to social housing providers.
- The assessment indicates that Jersey’s rental model reflects a dual approach, combining both market- and income-based elements to support affordability and financial sustainability.
Extracts from the executive summary of the substantive policy paper Review of social housing rents are set out below –
The review finds that Jersey’s existing market-based rental model – where rents are set at up to 80% of market value and affordability is supported through the housing component of Income Support – has been broadly effective in providing good-quality homes for low-income households and maintaining the financial stability of social housing providers. However, a number of challenges and unintended consequences have emerged since the implementation of this rental structure, including:
-
- inconsistencies between rent levels for older and newer tenancies;
- reduced incentives for tenants to right-size;
- increasing operational cost pressures on social housing providers; and
- areas where rental processes and Income Support could be more effectively aligned.
- In considering how best to respond to the issues identified, five policy options were developed and assessed against six Critical Success Factors relating to affordability, financial sustainability, feasibility, public benefit and equity. The five options are:
- 1. Maintain the current social housing rental model (no change)
- 2. Amendments to the current social housing rental model (minor change)
- 3. Reduce rents to an alternative market-based level, e.g. 70% (medium change)
- 4. Increase rents to an alternative market-based level, e.g. 90% (medium change)
- 5. Adopt an income-based social housing rental model (major change)
The review concludes that large-scale structural reforms, such as adopting an income-based rental model, would create significant administrative complexity and financial uncertainty, with limited additional benefit when the current role of Income Support in supporting eligible low-income households is taken into account.
Overall, the review finds that targeted amendments to the current rents policy (Policy Option 2) represent the most effective and proportionate way forward. This approach preserves the core structure of the existing rental model and supports refinements to the rents policy and related Income Support policies as evidenced through the review.
These amendments would create a fairer rental structure for tenants, strengthen the long-term financial sustainability of social housing providers and promote the efficient use of the housing stock. Importantly, they ensure that eligible households continue to have their full rent recognised by Income Support.
Further information
The following papers contain useful background information.
- Objective Assessment of Housing Need, by the consultants ARC4, January 2019.
- Review of Access to Social Housing in Jersey, by the consultants HQN, April 2019.
- Affordable Housing – Supply and Delivery, by the Environment, Housing and Infrastructure Scrutiny Panel, including a report by its consultants ARK, October 2021.
- Jersey Homelessness Strategy, report by the Jersey Homelessness Strategic Board, November 2020.
- Jersey Housing Market Review, report by Arup, May 2022.
Statistics Jersey publishes statistics on all aspects of housing.
